
Executive Overview
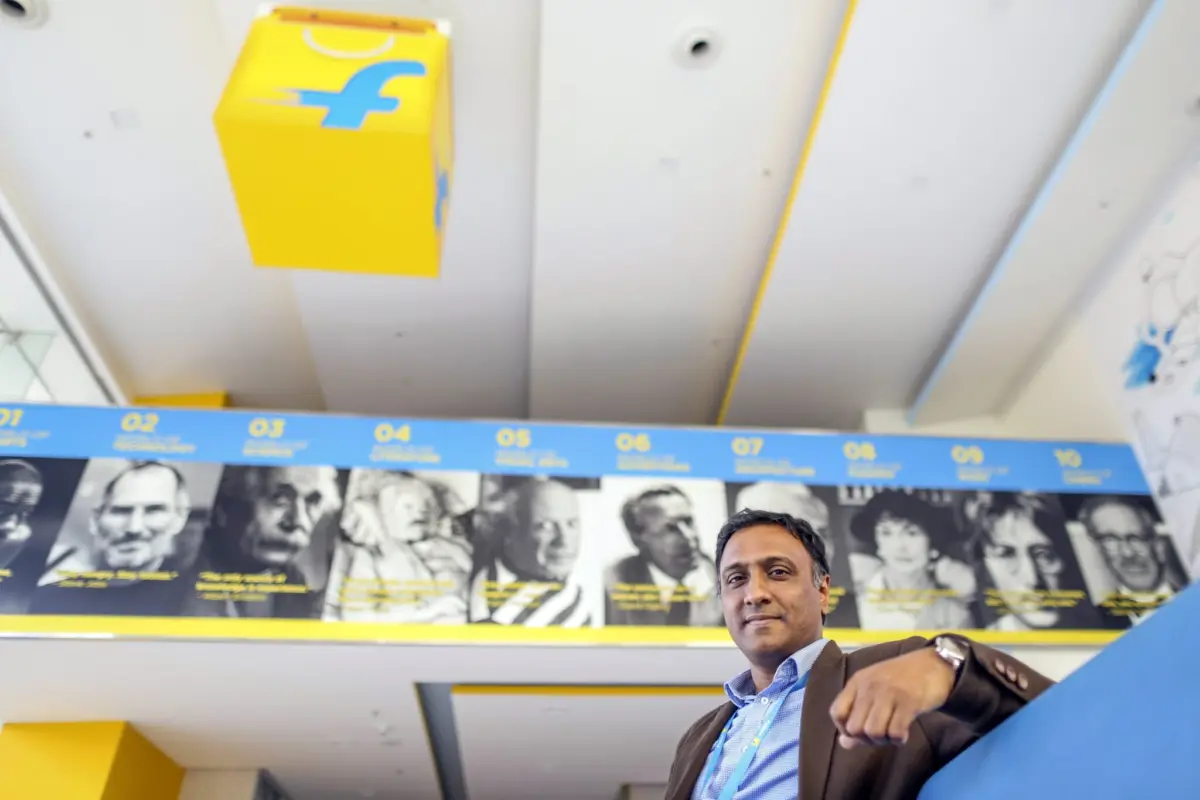
India’s fiercely contested digital commerce ecosystem is bracing for a high-stakes turf war. Flipkart, the Walmart-backed e-commerce titan, is aggressively preparing to challenge the entrenched food-delivery duopoly of Zomato and Swiggy. Operating out of its headquarters in Bengaluru, the company is quietly scaling internal trials of a new food-delivery service, expanding its testing pool from a few hundred corporate testers to upwards of 8,000 employees.
This calculated move marks Flipkart’s latest maneuver to capture daily consumer habits in the world’s most populous nation, home to more than a billion internet subscriptions. Yet, the road ahead is fraught with history. Flipkart is stepping into a brutally competitive arena that has previously defeated deep-pocketed global giants like Amazon and Google, while forcing ride-hailing pioneer Uber to retreat entirely.
Unlike its predecessors, however, Flipkart is approaching the market backward. Rather than building a food-delivery infrastructure first and expanding into adjacent retail sectors later—the playbook used by Zomato and Swiggy—Flipkart is leveraging its massive, established e-commerce architecture and its burgeoning quick-commerce subsidiary, "Minutes." By capitalizing on integrated logistics via its dedicated arm, Ekart, and tapping into both direct restaurant partnerships and the government-backed Open Network for Digital Commerce (ONDC), Flipkart aims to rewrite the economics of Indian food delivery.
With restaurant associations heavily criticizing the exorbitant commission fees levied by existing monopolies, and alternative challengers like ride-hailing firm Rapido also entering the fray, the Indian food-tech sector stands at a critical juncture. For Flipkart, this expansion is not merely a diversification play; it is a vital strategic evolution designed to drive higher app-engagement frequencies as the company navigates an intensely competitive quick-commerce landscape and an uncertain path toward an initial public offering (IPO).
Detailed Chronology: From Internal Tests to Public Ambitions
The evolution of Flipkart’s food-delivery initiative highlights a methodical, low-profile deployment strategy designed to stress-test technology, logistics, and vendor relations before facing the scrutiny of the general public.
Phase 1: Internal Prototyping and Employee Trials
Flipkart’s foray into food delivery did not begin in the open market. According to industry insiders familiar with the development, the Bengaluru-based e-commerce giant spent months quietly developing the infrastructure behind closed doors. Initially limited to a few hundred tech workers, the internal trial was recently scaled to encompass more than 8,000 employees.
Within the primary Flipkart shopping application, the service manifests as a dedicated, seamless tab. Positioned alongside established offerings such as the "Minutes" quick-commerce platform and the company’s travel-booking portals, the food-delivery interface grants employees access to a curated selection of culinary options. These menus draw from a hybrid ecosystem: direct partnerships forged by Flipkart’s business development teams and restaurants integrated through the Open Network for Digital Commerce (ONDC), India’s ambitious government-backed protocol designed to democratize digital commerce.
Phase 2: Hitting the Streets of Bengaluru
As the employee-only trial matured, Flipkart transitioned from digital testing to real-world operational stress tests. Eagle-eyed residents in Bengaluru began noticing a new breed of delivery personnel navigating the city’s notoriously congested traffic arteries. These couriers, outfitted in distinct jerseys bearing the branding "Eat-in by Minutes," are deployed through Ekart, Flipkart’s proprietary logistics and supply-chain subsidiary. Crucially, these riders operate within a dedicated fleet, completely separate from the couriers handling quick-commerce grocery and household deliveries, ensuring specialized handling for perishable food items.
Phase 3: The Upcoming Public Rollout
Flipkart’s leadership has communicated aggressive timelines to restaurant partners and industry stakeholders. According to high-level briefings, the company is positioning itself for a public rollout of the food-delivery service in Bengaluru by the end of October. Furthermore, the expansion blueprint does not intend to keep the service localized for long. Flipkart has signaled its intent to scale operations to five or six major Indian metropolitan areas before the close of the year, signaling a rapid national push designed to capture market share before competitors can effectively counter.
Supporting Context & Metrics: The Anatomy of a Trillion-Dollar Market
To understand the magnitude of Flipkart’s gamble, one must examine the macro-economic realities of India’s food-services and digital delivery sectors.
Market Dynamics and Growth Projections
According to data compiled by brokerage firm Bernstein, India’s online food-delivery market is expanding at a robust annual rate of 18% to 20%. Despite this impressive growth trajectory, online delivery remains heavily underpenetrated, accounting for just over 15% of India’s broader, multi-billion-dollar food-services industry.
The vast majority of the market remains dominated by dining out, traditional local takeout, and unorganized local vendors. This structural gap presents an enormous runway for aggressive newcomers. Bernstein estimates that the current market leaders, Zomato (owned by Eternal) and Swiggy, collectively serve between 85 million and 95 million paying customers annually. While these figures underscore the sheer dominance of the duopoly, they simultaneously highlight the massive untapped potential remaining in a nation boasting more than a billion internet subscriptions.
The Commission and Cost Burden
For years, restaurants across India have chafed under the economic models imposed by the Zomato-Swiggy duopoly. Sagar Daryani, president of the New Delhi-headquartered National Restaurant Association of India (NRAI)—an organization representing over 500,000 eateries nationwide—did not mince words regarding the current market structure.
"Monopoly is bad, but duopoly is more pathetic," Daryani stated, emphasizing that restaurants have long sought viable alternatives to escape the pricing power of the two dominant platforms.
Under standard industry models, restaurants typically pay Zomato and Swiggy base commissions ranging from 20% to 25%. However, Daryani points out that commissions represent only the tip of the iceberg. Once mandatory advertising expenditures, platform discounts, and other promotional overheads are factored into the equation, dining establishments can find themselves surrendering a staggering 40% to 50% of an order’s total gross value to the platforms.
In contrast, Flipkart is reportedly courting vendors with a much leaner financial proposal: a base commission of approximately 10%. Industry analysts and restaurant executives project that Flipkart’s streamlined supply chain could keep total operational and promotional costs closer to 15% to 16% for vendors. This drastic reduction promises to dramatically alter unit economics for restaurants, allowing them to retain a significantly higher percentage of revenue per order.
The Incumbent Counter-Offensives
Flipkart is not the sole disruptor attempting to crack the duopoly. The competitive landscape is shifting rapidly on multiple fronts:
- Rapido’s Zero-Commission Play: Ride-hailing challenger Rapido—which has successfully contested Uber and Ola in India’s ride-sharing market—has initiated tests for "Ownly," a food-delivery service operating on a zero-commission model for restaurants.
- Swiggy’s Budget App: Sensing pressure from cost-conscious consumers and alternative platforms, Swiggy has launched "Toing," a standalone mobile application specifically engineered to cater to users seeking affordable, budget-friendly meal options in the Delhi-NCR region.
These concurrent developments reflect mounting structural fatigue with traditional platform pricing models and signal that the Indian food-tech space is entering a hyper-competitive war for both restaurant partnerships and consumer loyalty.
Official Statements & Industry Perspectives
The entry of a tech heavyweight like Flipkart has elicited strong reactions from industry executives, restaurant coalitions, and financial analysts.
The NRAI Perspective: A Structural Advantage
Sagar Daryani, who also serves as the co-founder and CEO of popular dumpling chain Wow! Momo Foods, highlights a fundamental strategic divergence between Flipkart and previous market entrants. While Amazon, Uber, and Google attempted to build standalone food-delivery arms from scratch, Flipkart is inverting the model.
"Flipkart’s quick commerce benefit will get passed on to food delivery, so it will be leaner, more efficient," Daryani explained to tech analysts.
By building upon an existing e-commerce infrastructure—utilizing established warehousing, massive user bases, and the "Minutes" quick-commerce network—Flipkart avoids the prohibitive customer-acquisition and logistical startup costs that historically crippled foreign tech giants.
The Ghost of Failures Past
Market observers remain cautiously analytical, recalling the high-profile retreats of other multinational titans. The graveyard of India’s food-delivery sector includes several notable casualties:
- Amazon (2020–2022): Amazon launched its proprietary food-ordering service in Bengaluru in May 2020 amid pandemic-driven demand, only to shutter the division two years later as growth stagnated against entrenched local players.
- Google Areo (2017): Google introduced the Areo app to aggregate food delivery and home services in select Indian cities, but the application failed to capture meaningful market traction and was quietly decommissioned.
- Uber Eats India (2020): After severe cash-burning competition, ride-hailing giant Uber surrendered its Indian food-delivery footprint, offloading its Uber Eats assets to Zomato in an all-stock transaction valued at approximately $206 million.
Daryani and other retail analysts believe Flipkart’s localized ecosystem, deep integration with ONDC, and existing supply-chain muscle give it a fighting chance where Amazon and Google stumbled. Yet, consumer habits remain notoriously sticky. Bernstein notes that operational efficiencies might only translate to minor savings of ₹20 to ₹30 (roughly 20 to 30 cents) per order for consumers—a margin too slim to automatically induce mass migration away from Zomato and Swiggy, especially if incumbents respond with aggressive discounting campaigns.
Future Outlook: Quick Commerce Convergence and Corporate Strategy
Beyond food delivery, Flipkart’s operational maneuvers must be viewed through the lens of its broader corporate trajectory and the fierce convergence of India’s digital retail sectors.
The Quick-Commerce Battlefield
The traditional boundaries separating e-commerce, grocery delivery, and food tech are rapidly dissolving in India. Quick-commerce platforms—which initially promised grocery deliveries within ten to fifteen minutes—have aggressively expanded their product catalogs. Today, Indian consumers can acquire premium electronics, home appliances, and even the latest Apple iPhones via quick-commerce apps faster than a traditional pizza delivery. This rapid inventory expansion pits quick-commerce players directly against traditional e-commerce giants like Flipkart and Amazon.
By layering food delivery onto its application architecture, Flipkart is engineering a defensive and offensive moat designed to maximize user retention and daily app engagement.
IPO Timelines and Walmart’s Calculus
This ambitious expansion coincides with persistent industry speculation regarding Flipkart’s long-awaited initial public offering (IPO). While market watchers continually scan for public market milestones, Flipkart’s leadership has maintained a measured stance. Chief Executive Kalyan Krishnamurthy recently declined to commit to a definitive timetable for an IPO during media briefings, opting instead to focus the company’s capital allocation on high-frequency consumption categories like quick commerce and, now, food delivery.
Conclusion: Can Flipkart Win?
As Flipkart prepares for its public launch in Bengaluru this October and eyes multi-city expansion by year’s end, the stakes could not be higher. Breaking a duopoly supported by billions in venture capital and deeply ingrained consumer habits requires more than deep pockets—it demands operational precision, vendor trust, and a compelling value proposition that transcends minor price differentials.
If Flipkart can successfully weaponize its quick-commerce infrastructure and deliver on its promise of lower commission burdens for restaurants, it may finally crack a code that baffled Amazon and Google. If it fails, it will serve as another cautionary tale of the brutal economics governing India’s digital consumer market. For now, the kitchen doors are open, and the battle for India’s dinner table is officially underway.
Belum ada komentar. Jadilah yang pertama berkomentar!