

Executive Overview
The venture capital ecosystem is undergoing a historic realignment, driven by the meteoric rise of artificial intelligence giants like OpenAI and Anthropic. At the center of this transformation are limited partners (LPs)—the institutional investors, university endowments, pension funds, and family offices that act as the "money behind the money." Today, these elite allocators find themselves in deeply unfamiliar yet potentially lucrative territory.
Traditionally, the golden rule of venture capital investing was strict portfolio diversification. LPs spread their bets across a broad spectrum of funds: emerging managers and established institutions, generalists and niche specialists. The foundational goal was simple—maximize returns while aggressively mitigating downside risk through strategic dispersion.
In the current AI-dominated market, however, that classic playbook has been completely thrown out the window. Valuations for foundational AI developers have skyrocketed at an unprecedented velocity, compelling nearly every major venture firm to pile into the exact same crown-jewel assets. This widespread consolidation has effectively shattered the longstanding venture convention against backing conflicting competitive portfolio companies. Yet, remarkably, few are complaining. While institutional allocators anticipate a historic financial bonanza, they are simultaneously navigating a complex web of structural warnings: compressed fund-raising cycles, soaring check sizes, and intense pressure on portfolio liquidity.
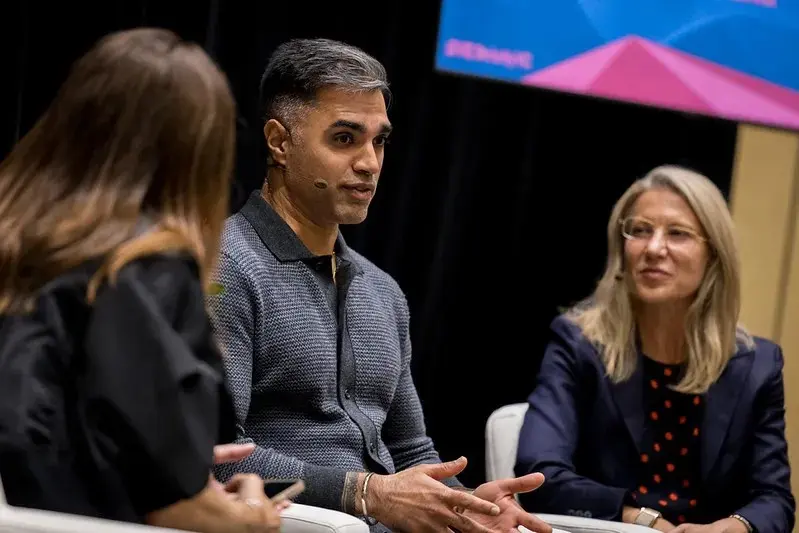
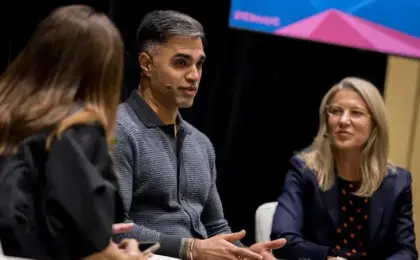
To unpack these dynamics, we sat down with two prominent industry veterans: Beezer Clarkson, managing director at Zurich-based diversified asset manager LGT Capital Partners, and Amit Bhatti, managing director at TrueBridge, a Chapel Hill firm dedicated exclusively to venture capital. Their insights reveal an industry hurtling forward at breakneck speed, balancing exhilarating upside against lingering systemic risks.
Detailed Chronology: The Evolution of the Modern AI Venture Cycle
To understand how the venture landscape reached its current fever pitch, it is necessary to examine the rapid acceleration of investment pacing and market dynamics over recent years.
The Pandemic Era and Accelerated Vintages (2020–2021)
The seeds of today’s market acceleration were planted during the zero-interest-rate policy era of the COVID-19 pandemic. Capital flooded into private markets at historic rates, driving valuations to unsustainable highs. During this period, traditional four-year venture fund investment cycles began shrinking to three years, and occasionally down to two. LPs faced unprecedented capital calls to support high-flying startups, many of which later struggled to justify their inflated pandemic-era valuations.
The GenAI Gold Rush and Compressed Timelines (2023–2024)
As generative AI exploded into the mainstream following the public launch of ChatGPT, investment pacing collapsed even further. Venture funds that historically deployed capital over a 36-month window began returning to LPs for fresh capital after just 12 to 18 months. This rapid compression was driven largely by the sheer capital intensity of AI infrastructure. Mega-rounds for companies like OpenAI and Anthropic commanded billions of dollars, forcing venture managers to allocate massive chunks of their dry powder into single assets to maintain ownership stakes.
The Current Market Landscape (2025–2026)
Today, the venture market is characterized by a polarized reality. On one hand, exceptional liquidity events—such as secondary market transactions, massive enterprise software acquisitions, and mega-IPOs like SpaceX—have unlocked billions in capital returns. On the other hand, LPs are grappling with the structural strain of continuous capital calls against a backdrop of delayed traditional exits, forcing institutional allocators to strictly monitor their portfolio pacing and liquidity exposure.
Supporting Context & Metrics: The Mechanics of Modern Venture Concentration
The current market cycle defies historical precedent in several measurable ways, fundamentally altering how capital flows through the private equity and venture ecosystem.
Power Law Concentration vs. Diversification
Venture capital has always operated under a strict power law distribution, where a tiny fraction of portfolio companies generates the vast majority of all financial returns. However, the degree of concentration in the current cycle is unprecedented.
In a mature, healthy vintage, top-performing funds naturally consolidate around proven category leaders—historically names like Stripe, Databricks, and SpaceX. In the current generation of funds, that consolidation is heavily concentrated around OpenAI and Anthropic. While traditional allocators might view this lack of diversification as a risk, experienced LPs argue that it is a fundamental feature of high-performing venture portfolios. If a 10-year-old fund still holds dozens of tiny, irrelevant positions, something has structurally failed.
The Compression of Fund-Raising Pacing
The shift from 36-month fund deployment cycles to 12-to-18-month cycles has introduced significant friction for institutional investors. This acceleration is exacerbated by two primary market forces:
- Mid-Cycle Fund Upsizes: Rather than returning to market with an entirely new fund vehicle, many managers are bumping up the size of their existing funds mid-cycle to accommodate ballooning check sizes.
- Escalating Seed Round Economics: Seed-stage check sizes have nearly doubled over the past several years, requiring early-stage managers to deploy larger blocks of capital simply to secure lead positions in competitive deals.
Despite these warning signs—which institutional allocators describe as a "yellow light" situation—industry veterans note a crucial qualitative difference between this cycle and past frenzies. Unlike the speculative, zero-revenue crypto moonshots of previous years, many AI-native companies are rapidly scaling from zero to $100 million in annual recurring revenue at speeds previously thought impossible.
Official Statements: Perspectives from Market Insiders
The complexities of managing institutional capital through an unprecedented market expansion are best understood through the perspectives of those leading the charge.
Navigating Chaos and Excitement
Discussing the psychological climate of the current startup ecosystem, industry leaders emphasize experience over panic.
"It’s very busy, but I wouldn’t say it’s scary," notes Beezer Clarkson of LGT Capital Partners. "There’s a lot of change and a lot of variables at play. I love venture, so I find the chaos fun. I’ve been doing this for a couple of decades, so seeing the cycles makes it less scary. You appreciate that these things happen, and that we should enjoy the upside, because sometimes there’s downside, and the up is a lot more fun than the down."
Echoing this sentiment, Amit Bhatti of TrueBridge highlights the cultural shift in how venture capital is perceived globally:
"If anything, it’s exciting. Venture is sometimes looked at as a niche, and now that AI is all-consuming, all the attention is on venture. This feels like our moment more than it is like, ‘Oh gosh, what’s going to happen?’ The pace of investing and the valuations may be different, but really meaningful stuff is happening, and all the attention is focused on this corner of private equity."
The Secondary Market Evolution
One of the most profound structural shifts in the modern venture ecosystem is the maturation of the secondary market. Once viewed as a sign of financial distress or corporate weakness, secondary transactions have evolved into the "third leg of liquidity," sitting alongside traditional IPOs and M&A exits.
"Secondaries have become much more sophisticated in venture over the last five years," Clarkson explains. "It’s localized in the top handful of companies, but it’s much more prevalent than before… Venture is predicated on liquidity options, and if you wait 20 years for an IPO, that is not what structurally we all thought it could be."
Bhatti adds that managers are now utilizing secondaries with strategic precision:
"If you still believe it’s a power law company, you’re probably not exiting the whole position. But if you can sell 20% of your position and return your fund, you should probably do it."
Future Outlook: Emerging Managers, Geographic Concentration, and the Road Ahead
As the venture ecosystem looks toward the remainder of the decade, several critical questions remain regarding structural sustainability, geographic dominance, and the fate of emerging managers.
The Resiliency of the Bay Area and Geographic Hubs
Despite soaring real estate and living costs in San Francisco—which threaten to price out incoming generations of founders and tech workers—the Bay Area’s deep-rooted density advantage remains largely unassailable. While secondary tech hubs like New York continue to expand their technological footprints, the historical agglomeration of talent, technical expertise, and venture capital infrastructure ensures that Northern California will retain its status as the global epicenter of artificial intelligence innovation.
The Survival and Strategy of Emerging Managers
While institutional capital increasingly flows toward mega-funds, a vibrant ecosystem for emerging managers (Funds I through III) persists. Fundraising has undeniably grown more rigorous, but smaller, highly specialized funds—ranging from $5 million micro-funds to $50 million early-stage vehicles—continue to find strong backing.
Institutional allocators are increasingly willing to support nontraditional emerging managers, including student-led accelerators at elite institutions like MIT, Stanford, and Harvard, as well as operators investing on the side. These nimble funds leverage hyper-proximate access to top-tier technical talent, giving them an early edge in sourcing category-defining AI-native startups.
Conclusion: A Calculated Optimism
Ultimately, today’s limited partners are steering through uncharted territory with a blend of calculated optimism and disciplined caution. While compressed fund-raising cycles and outsized capital concentrations present genuine operational hurdles, the transformative potential of artificial intelligence continues to redefine the boundaries of private markets. For the allocators bankrolling the future, the primary challenge will not be finding capital deployment opportunities, but maintaining portfolio discipline as the AI revolution accelerates.

Belum ada komentar. Jadilah yang pertama berkomentar!